If I had a dollar for every misconception or myth I’ve heard about VA home loans, well… I might have enough to cover somebody’s closing costs! 😂
Seriously, though, there are a LOT of misunderstandings about VA financing.
And the frustrating part? Some of those myths actually keep eligible veterans from buying homes or cause sellers to hesitate when they receive a perfectly good VA offer.
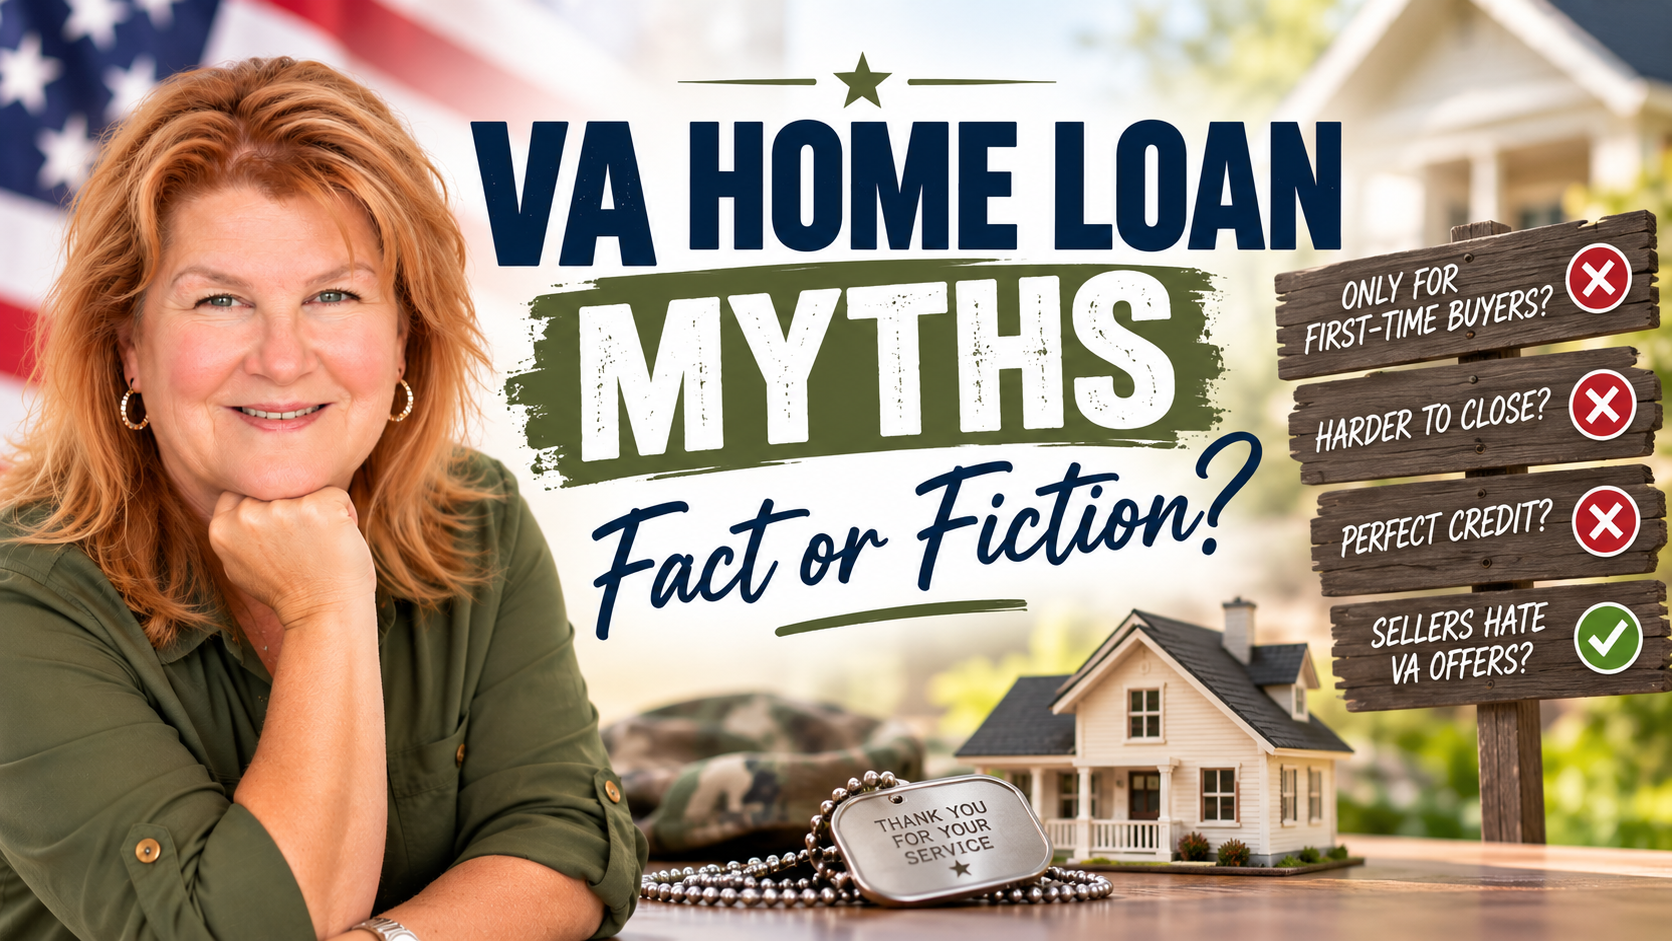
So today, we’re separating FACT from FICTION.
Let’s get into it!
Myth #1: VA Home Loans Are Only for First-Time Homebuyers
⛔FICTION!
This is one of the biggest misconceptions about VA financing.
Your VA home loan benefit isn’t a one-time coupon that expires after your first house.
Eligible veterans and service members may be able to use their VA benefit multiple times throughout their lives.
In some situations, you may even be able to have more than one VA-financed property at a time, provided you have sufficient entitlement, meet loan requirements, and satisfy the applicable occupancy rules.
Whether you’ve used your benefit before or are buying your very first home, it’s worth exploring your options.
Myth #2: You Have to Have Perfect Credit to Qualify for a VA Loan
⛔FICTION!
This one is especially important to me because I’ve seen how many people assume their credit score automatically disqualifies them.
The Department of Veterans Affairs does not establish a universal minimum credit score for VA loans.
Now, individual lenders and investors may have their own minimum score requirements, called overlays.
And here’s where having the right lending options makes a difference: I work with investors who offer VA programs without a minimum credit-score overlay.
That doesn’t mean everyone automatically qualifies. We still have to evaluate credit history, income, debts, residual income, and the overall loan application.
But I certainly don’t want you counting yourself out because of a number before we’ve even had a conversation!
Want to understand your credit better? Visit my Credit Score for Buying a Home resource.
Myth #3: VA Loans Take Forever to Close
⛔FICTION!
VA loans aren’t automatically slower than conventional or FHA loans.
Like any mortgage, the closing timeline depends on the transaction, how quickly documentation is provided, the appraisal, title work, underwriting, and whether unexpected issues arise.
A well-prepared VA loan can move along quite efficiently.
The important thing is working with a team that understands VA requirements, knows how to anticipate potential obstacles, and communicates throughout the process.
Not every delay is a VA delay, my friends!
Myth #4: VA Appraisals Are Impossible to Pass
⛔FICTION!
VA appraisals have a reputation for being unusually difficult.
But the purpose of the VA’s Minimum Property Requirements is to help ensure that the home meets basic standards for being safe, structurally sound, and sanitary.
A VA appraiser is not looking for reasons to reject every house with a squeaky door or outdated paint color.
There can be legitimate property concerns, such as exposed wiring, certain safety hazards, or significant deterioration that needs to be addressed.
But normal wear and tear doesn’t automatically make a home ineligible.
And remember, a VA appraisal is NOT a home inspection.
The appraisal provides an opinion of value and evaluates applicable minimum property requirements. A professional home inspection provides a much more detailed assessment of the home’s condition.
We’re also creating a separate resource dedicated to understanding VA appraisals and common misconceptions.
Myth #5: Sellers Should Avoid VA Offers
⛔FICTION!
This one drives me a little crazy!
There’s a persistent belief that a VA offer is somehow less attractive simply because the buyer is using VA financing.
But financing type alone doesn’t tell the seller whether an offer is strong.
What really matters includes the buyer’s financial qualifications, the terms of the contract, the property condition, the lender’s preparation, and the ability of everyone involved to meet the closing timeline.
VA loans have certain requirements that need to be considered, but they also provide tremendous benefits to eligible buyers.
A strong VA prequalification, realistic contract terms, and good communication can go a long way toward reassuring sellers.
Veterans have earned their benefit. Their offers deserve fair consideration, too.
Myth #6: You Need a Down Payment for a VA Loan
FICTION — in many cases!
One of the best-known VA loan benefits is the possibility of buying a home with no down payment.
Eligible buyers with sufficient entitlement may be able to finance 100% of the eligible purchase price, subject to appraisal and lender requirements.
However, not every situation qualifies for zero down.
For example, a down payment may be necessary if you don’t have enough remaining entitlement or if the purchase price exceeds the property’s supported value and you choose to proceed.
And remember: Zero down payment doesn’t necessarily mean zero cash to close.
There may still be closing costs, prepaid expenses, earnest money, inspections, and other expenses.
I’ve created a separate guide explaining those costs in detail: VA Loan Closing Costs & Funding Fees: What Buyers Need to Know.
Myth #7: You Can Only Use a VA Loan to Buy a Traditional Single-Family House
⛔FICTION!
VA loans aren’t limited to one specific style of home.
Depending on eligibility, property requirements, and lender guidelines, VA financing may be available for several property types, including:
- Traditional single-family homes
- Eligible condominiums
- Certain manufactured homes
- Eligible two- to four-unit properties
- Some new-construction transactions
The important thing is that the property meets VA requirements and any applicable lender or investor guidelines.
VA loans are generally intended for a home you will occupy as your primary residence, not a property you’re purchasing solely as an investment.
If you’re considering a manufactured home, acreage, or an unusual property, talk with me before getting too far into the shopping process.
That’s exactly the kind of puzzle I enjoy helping solve!
Myth #8: Once You’ve Used Your VA Benefit, You’ve Used It Up
⛔FICTION!
Your VA home loan benefit can often be restored or reused.
If you’ve sold a home financed with a VA loan and paid the loan off, you may be eligible to request restoration of the entitlement used.
There are also circumstances where borrowers may use remaining entitlement without selling their existing property.
And in certain situations, a veteran who has paid off the prior VA loan but still owns the home may qualify for a one-time restoration of entitlement.
The details matter, and restoration isn’t automatic.
But if someone has told you that buying one home means your VA benefit is gone forever, I’d love the opportunity to review your situation.
Myth #9: VA Loans Have a Maximum Purchase Price
FICTION — for borrowers with full entitlement!
You may remember hearing about VA county loan limits.
But eligible borrowers with full VA entitlement generally don’t have a VA-imposed county loan limit on the amount they can borrow.
That doesn’t mean unlimited borrowing power, of course!
You still have to qualify for the mortgage, and the property must support the loan amount.
Borrowers with partial entitlement may have different down-payment considerations.
The purchase price, appraised value, remaining entitlement, income, and overall qualifications all matter.
Myth #10: The VA Gives You the Mortgage Directly
FICTION — for most VA home purchase loans!
With a typical VA-backed purchase loan, the mortgage comes from a private lender, not directly from the Department of Veterans Affairs.
The VA guarantees a portion of the loan, which can help participating lenders offer favorable financing terms to eligible borrowers.
That distinction matters because lenders can have different loan programs, rates, fees, and underwriting requirements.
And it’s one reason the lender you work with can make a difference.
Don’t Let a Mortgage Myth Make Your Decision for You!
Here’s what I really want you to remember:
Your VA home loan benefit is too valuable to dismiss based on something you’ve heard from a friend, a neighbor, or somebody’s cousin who bought a house fifteen years ago. 😂
The rules aren’t always what people think they are.
And sometimes the financing option that seems impossible at first deserves a closer look.
Whether you’re buying your first home, considering another purchase, or simply wondering whether you qualify, I’m happy to help you sort through the facts.
Or call or text me at 918-316-7237.
Keep Learning About VA Home Loans
Explore my VA Home Loan Resource Center for educational articles, videos, and helpful information about VA financing.
You can also read my VA Home Loan FAQs for answers to questions I hear from borrowers.
Lisa Pinnick | Senior Mortgage Loan Officer | All Western Mortgage | NMLS #1810532
All financing is subject to eligibility, credit approval, property requirements, and applicable lender guidelines. VA home loan guarantees are provided by the U.S. Department of Veterans Affairs. All Western Mortgage is not affiliated with or endorsed by the Department of Veterans Affairs. Additional licensing and company disclosures may apply.
Published October 2026. Program guidelines are subject to change.